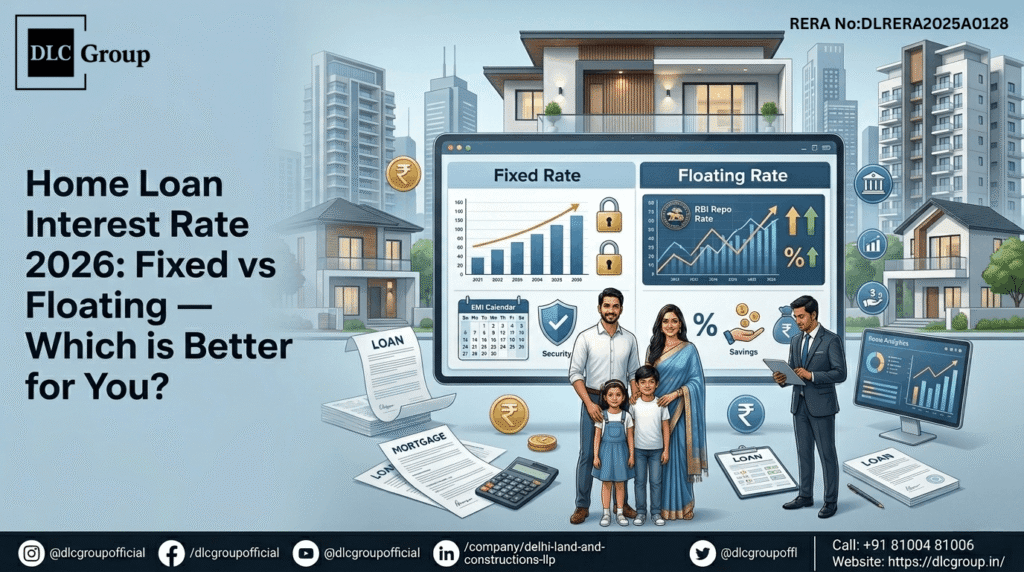
Buying a home is one of the biggest financial decisions of your life. Therefore, choosing the right Home Loan Interest Rate matters more than most borrowers realise. In 2026, with the RBI fine-tuning the repo rate and lenders competing aggressively, you have a real chance to save lakhs over the loan tenure.
However, the big question still remains the same. Should you pick a Fixed Interest Rate Home Loan for stability, or go with a Floating Interest Rate Home Loan for potential savings? This guide breaks down both options in simple terms so you can decide with confidence.
The Home Loan Interest Rate 2026 landscape looks more borrower-friendly than the previous years. Banks and housing finance companies currently offer rates between 8.10% and 9.50% per annum. Moreover, several lenders run special festive offers with processing fee waivers.
Your final rate depends on your credit score, income profile, and the loan-to-value ratio. Therefore, before applying, check your CIBIL score and clean up any pending dues.
The RBI Repo Rate Home Loan Impact is direct and immediate. When the RBI cuts the repo rate, floating loans become cheaper almost instantly. Conversely, when rates rise, your EMI also goes up.
Fixed-rate loans, however, stay unaffected. For example, if you locked in a fixed rate of 9% last year, repo rate changes will not touch your EMI for the agreed period.
A Fixed Interest Rate Home Loan keeps your interest rate constant throughout a defined period. As a result, your EMI stays the same month after month. This makes monthly budgeting predictable and stress-free.
Fixed rates usually sit 1% to 2% higher than floating rates. Additionally, if the RBI cuts rates, you miss out on the savings. Furthermore, prepayment penalties may apply if you close the loan early.
A Floating Interest Rate Home Loan changes based on the lender's benchmark rate, usually linked to the RBI repo rate. Therefore, your EMI or tenure adjusts whenever the rate moves.
Floating rates can rise without warning. Consequently, your EMI may stretch your monthly budget. Moreover, planning long-term finances becomes slightly tricky.
Here is a clear breakdown of Fixed vs Floating Home Loan features for easy comparison.
| Feature | Fixed Rate | Floating Rate |
|---|---|---|
| Interest Rate | Higher (9.5%–10.5%) | Lower (8.1%–9.5%) |
| EMI Stability | Stable | Changes with market |
| Market Risk | None | Present |
| Prepayment Charges | May apply | None (for individuals) |
| Best For | Risk-averse borrowers | Long-term planners |
Your choice depends on your personal situation. Therefore, ask yourself a few honest questions before signing the loan agreement.
Yes, absolutely. Borrowers often want to Switch from Fixed to Floating Home Loan when market rates drop. Most banks allow this through a simple conversion process and a small fee, usually 0.5% to 1% of the outstanding amount.
Finally, always read the fine print. Some lenders charge hidden fees during conversion.
The right Home Loan Interest Rate can save you several lakhs over the loan tenure. Therefore, never rush the decision. Fixed rates suit cautious planners, while floating rates reward patient long-term borrowers.
Furthermore, always review your loan every 2–3 years. If better rates appear in the market, switch without hesitation. Finally, remember that a good loan is not just about the lowest rate — it is about flexibility, transparency, and the right partner.
Our loan advisors compare 25+ banks and find the lowest interest rate for your profile — completely free.
📞 Talk to an Expert NowHome loan interest rates in 2026 range between 8.10% and 9.50% per annum. However, your exact rate depends on your credit score, income, lender, and loan-to-value ratio.
Floating rates usually work better for tenures above 10 years. Historically, RBI rate cuts have made floating loans cheaper over the long term. Moreover, you face no prepayment penalty.
When the RBI changes the repo rate, banks adjust their lending rates accordingly. Therefore, floating home loan EMIs move up or down in line with these changes. Fixed loans, however, stay unaffected.
Yes, you can. Most banks allow this conversion for a small fee of around 0.5%–1% of the outstanding loan. Alternatively, you can opt for a balance transfer to another lender offering a better rate.
A CIBIL score of 750 or above unlocks the best home loan interest rates. Additionally, lenders consider your income stability, repayment history, and existing debts before finalising the rate.
No. As per RBI rules, individual borrowers face no prepayment charges on floating rate home loans. Therefore, you can prepay anytime and reduce your interest burden significantly.
Get personalised quotes, the lowest interest rate, and end-to-end guidance from our loan experts.
📞 Call 81004 81006Real Estate Advisory
