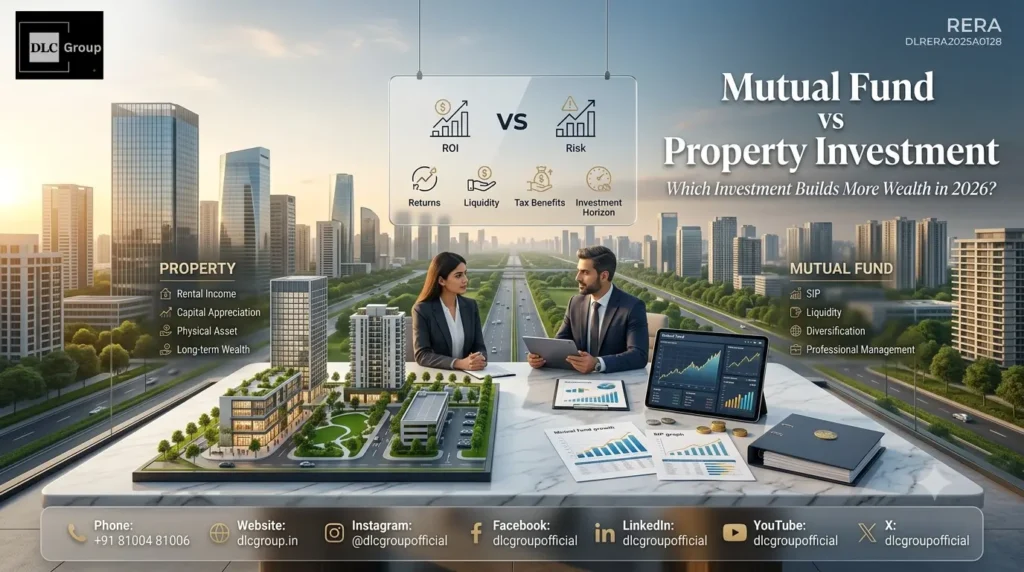
If you’ve ever sat down with a bonus, a maturing FD, or your first serious savings and wondered where to put it, you’ve probably landed on this exact question: Mutual Fund vs Property Investment — which one actually builds wealth faster, and which one is right for you?
There’s no single correct answer. A salaried professional in their late twenties has different needs than a business owner sitting on surplus cash, and an NRI planning a retirement home in India has different priorities than a first-time investor testing the waters with ₹5,000 a month. This guide breaks down both options honestly — returns, risk, liquidity, tax, and real-world numbers — so you can make a decision that fits your life, not someone else’s spreadsheet.
Mutual funds pool money from investors and put it into stocks, bonds, or a mix of both, managed by professional fund managers. You can start a SIP (Systematic Investment Plan) with as little as ₹500 a month, and your money is invested across dozens of companies instead of a single asset — this diversification is one of the biggest draws for first-time investors.
Returns aren’t guaranteed and depend on market performance, but historically, equity mutual funds in India have outperformed inflation over long horizons of 7-10+ years, though with meaningful short-term volatility.
Property investment means buying residential or commercial real estate — a plot, an apartment, or a shop — either to live in, rent out, or hold for future appreciation. If you’re evaluating options in the Delhi NCR belt, working with a qualified Real Estate Consultant can help you avoid title issues, approval delays, and overpriced listings, which are common pitfalls for first-time buyers.
Unlike mutual funds, real estate is illiquid — selling a property can take months — but it offers something SIPs don’t: a physical, usable asset, the option of rental income, and access to leverage through home loans.
Government-backed schemes have also made entry-level property investment more accessible. For instance, the Deen Dayal Awas Yojana is designed to make affordable housing achievable for a wider range of buyers, and projects like the DDJAY Plots in Pataudi Sector 4 are worth evaluating if you’re looking at plotted development in emerging micro-markets.
| Parameter | Mutual Funds | Property |
|---|---|---|
| Minimum Investment | ₹500 (SIP) | ₹5–50+ Lakhs typically |
| Liquidity | High (redeem in 1-3 days) | Low (weeks to months) |
| Diversification | High (across sectors/companies) | Low (single asset) |
| Passive Income | Dividends (variable) | Rental income (steady) |
| Capital Appreciation | Market-linked | Location-dependent |
| Leverage (Loans) | Limited | High (home loans widely available) |
| Maintenance Effort | None | Ongoing (repairs, tenants, taxes) |
| Entry/Exit Costs | Low (exit load, if any) | High (stamp duty, registration, brokerage) |
Risk: Mutual funds carry market risk and NAV fluctuates daily; equity funds especially can see sharp short-term drops. Property carries location risk, legal/title risk, and liquidity risk — your money can get “stuck” if the local market slows down.
Liquidity: This is where the two differ most. Mutual funds can typically be redeemed within a few working days. Property, even in a hot market, usually takes weeks to months to sell at a fair price.
Tax: Equity mutual fund gains held over a year are taxed as long-term capital gains, while property gains held over the specified holding period qualify for long-term capital gains treatment with applicable indexation benefits under current tax rules. Tax rules change periodically, so always verify current provisions on the SEBI or Income Tax Department website, or consult a tax advisor before investing.
| Mutual Funds | Property | |
|---|---|---|
| Pros | Low entry, high liquidity, diversified, professionally managed, easy to track | Tangible asset, rental income, loan leverage, emotional/utility value, inflation hedge |
| Cons | Market volatility, no physical asset, requires discipline to stay invested | Illiquid, high transaction cost, maintenance burden, market can stay flat for years |
Consider two investors, each starting with ₹50 lakh in 2016.
Investor A put the full amount into a diversified equity mutual fund and left it untouched for 10 years, riding out multiple market corrections along the way.
Investor B used the ₹50 lakh as a down payment plus loan to buy a 2BHK apartment in a growing NCR suburb, renting it out for modest monthly income while paying off the EMI.
Yes — and for many investors, this is the smarter approach. A common strategy is to build liquidity and market exposure through mutual fund SIPs while allocating a portion of surplus capital toward property once you’ve identified the right opportunity, such as options in developing corridors like Swarnim Sohna. This way, you’re not choosing between growth and stability — you’re building both.
There’s no universal winner in the Mutual Fund vs Property Investment debate. Mutual funds suit investors who prioritize liquidity, diversification, and a lower entry barrier, while property suits those seeking a tangible asset, rental income, or long-term capital appreciation with the ability to leverage a home loan. The right choice depends on your financial goals, investment horizon, risk appetite, and available capital — and for many people, a mix of both delivers the best of each world. If you’d like a second opinion tailored to Delhi NCR real estate specifically, Deepak Gupta and the team regularly guide investors through exactly this decision.
This article is for informational purposes only and does not constitute personalized financial or investment advice. Please consult a certified financial advisor before making investment decisions.
Get professional advice from DLC Group experts and explore the right property opportunities with trusted market insights.
📞 Talk to an Expert NowNeither is universally better — mutual funds offer liquidity and diversification with lower entry capital, while property offers a tangible asset and rental income. The right choice depends on your goals and risk tolerance.
Returns vary by market cycle, location, and fund choice. Equity mutual funds have historically delivered strong long-term growth, while property returns depend heavily on location and timing.
Mutual fund SIPs can start from ₹500/month, while property investment typically requires several lakhs upfront for down payment, stamp duty, and registration.
Property is often considered a natural inflation hedge since rents and property values tend to rise with inflation, though equity mutual funds have also historically outpaced inflation over long periods.
Yes, NRIs can invest in Indian mutual funds (subject to KYC/FATCA norms) and in residential or commercial property, though certain agricultural land purchases are restricted.
Both are subject to capital gains tax, with rates and holding periods differing by asset class. Rules change periodically, so verify current provisions with a tax advisor or on official government sources.
Property prices generally fluctuate less dramatically day-to-day than mutual fund NAVs, but real estate carries its own risks including illiquidity, legal issues, and location-dependent demand.
First-time investors with limited capital often start with mutual fund SIPs for flexibility and low entry cost, then consider property once they’ve built a larger capital base.
Yes — mutual funds can offer variable dividend payouts through certain schemes, while property offers rental income, though rental income tends to be steadier month-to-month.
Many financial planners suggest combining both — using mutual funds for liquidity and growth, and property for stability, rental income, and long-term appreciation.
Connect with our experts to understand how market insights can help you make better property decisions alongside your mutual fund portfolio.
📞 Call +91 81004 81006